UK Branch vs Subsidiary (2026): Which Should You Choose?
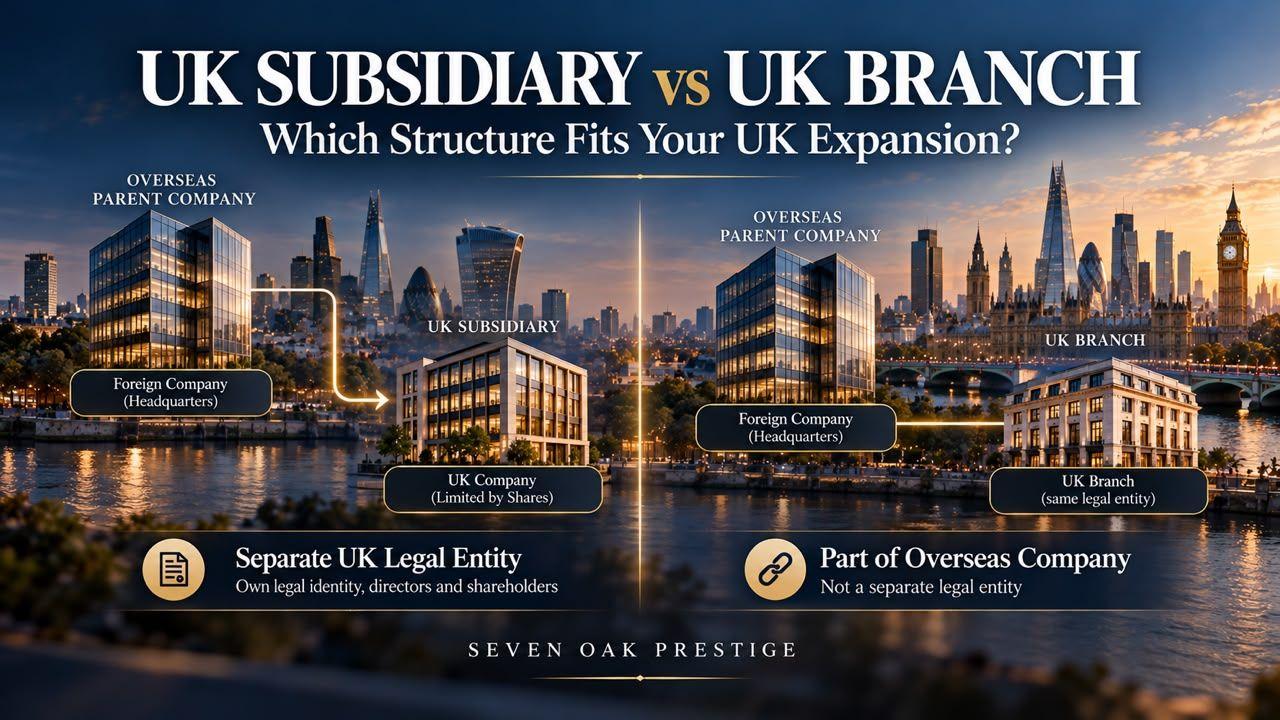
A UK subsidiary is a separate UK company owned by your overseas company: it signs its own contracts, carries its own risks and files its own accounts. A UK branch is your overseas company itself, registered in the UK as a "UK establishment": the parent stays directly liable, and it files the parent's accounts at Companies House.
For most overseas businesses that want to hire, sign UK contracts or open a UK bank account, a subsidiary is the simpler and safer choice. A branch suits a parent that deliberately wants to keep the UK activity inside its existing company and accepts the exposure. If you only need one or two UK staff, an Employer of Record may be enough for now.
UK branch vs subsidiary at a glance
Legal status
- Subsidiary: a separate UK company.
- Branch: part of the overseas company.
Who is liable for UK debts and contracts
- Subsidiary: the UK company, unless the parent gives a guarantee.
- Branch: the overseas parent, directly.
Companies House registration fee (2026)
- Subsidiary: £100 online incorporation.
- Branch: £124 to register a UK establishment (form OS IN01, paper filing only), within one month of opening.
Accounts made public in the UK
- Subsidiary: the UK company's own accounts.
- Branch: usually the overseas parent's accounts.
UK tax
- Subsidiary: Corporation Tax on all its profits.
- Branch: Corporation Tax on the profits linked to its UK activity.
Bank account and contracts
- Subsidiary: in its own UK name.
- Branch: in the overseas company's name.
Typical choice for
- Subsidiary: hiring a UK team, selling to UK enterprises, distribution, investment.
- Branch: an integrated office where the parent stays the contracting party.
Expanding into the UK? Tell us your parent company's country and what the UK operation will do; we'll tell you which structure fits and what it costs. Message us on WhatsApp (ref SOP-SUBBR-TOP).
The 8 differences that actually decide it
1. Liability: who pays if something goes wrong?
A subsidiary is a separate legal person, so UK debts and claims stay with the UK company. That protection is not absolute: landlords, banks and large customers often ask the parent to guarantee the subsidiary, and a signed guarantee makes the parent liable for that commitment.
A branch has no separation. Every UK contract, debt or claim is the overseas company's own.
2. Contracts and customers
A subsidiary signs in its own UK name, which many UK enterprise customers, public-sector buyers and suppliers prefer. A branch signs as the overseas company.
3. What becomes public at Companies House
This is often the deciding factor for private groups.
- Subsidiary: files its own UK accounts each year. Only the UK company's figures are published, though group transactions may be disclosed.
- Branch: the overseas company usually has to file its own accounts at Companies House. If the parent must publish accounts at home, they are generally due within three months of that home deadline; other rules apply if it doesn't. Filing costs £50 online or £110 on paper.
If you would rather not publish your whole group's figures in the UK, a subsidiary keeps them private.
4. Tax
Neither is automatically cheaper.
- Subsidiary: UK tax resident. Pays Corporation Tax on all its profits: 19% up to £50,000, 25% above £250,000, Marginal Relief in between. These limits are shared with associated companies, so in a group they are usually lower. Dealings with the parent need proper intercompany agreements and transfer pricing.
- Branch: pays UK Corporation Tax on profits attributable to its UK permanent establishment, worked out under UK law and the tax treaty. Attributing profits and head-office costs can be complex.
- Start-up losses: a branch's losses are the parent's own, and some home countries let them be used against home profits, others restrict it. A subsidiary's losses stay in the UK company. Ask your home-country adviser before choosing.
Registering a branch at Companies House and having a taxable "permanent establishment" are separate tests: you can have one without the other.
5. Banking
A subsidiary applies for a UK business account in its own name, with the parent's ownership reviewed. A branch applies as an overseas company, which many UK banks and payment providers find harder to onboard. No structure guarantees approval.
6. Hiring UK staff
Both can employ people and run UK payroll. A subsidiary makes the employer a UK company, which is simpler for contracts, pensions and, where needed, a sponsor licence.
7. Setup effort
A branch is not simpler to set up. It needs the parent's constitutional documents, often certified and translated, and details of the UK establishment. A subsidiary is a new UK incorporation, usually completed within 24 to 48 hours once documents and identity verification are ready. Step-by-step details are in How to Set Up a UK Subsidiary.
8. Exit and change
A subsidiary can be sold, given investors or closed on its own. Turning a branch into a subsidiary later is possible but means transferring contracts, staff, assets and tax registrations, with possible tax consequences. If you expect to grow, it is usually easier to start with a subsidiary.
Do you need a branch or subsidiary at all? The Employer of Record option
If your overseas company only wants to hire one or two people in the UK, an Employer of Record (EOR) can employ them for you and run UK payroll, for a monthly fee per employee, without any UK entity.
It works well for testing the market. It stops working when you need to sign UK contracts in a UK name, invoice UK customers locally, open a UK bank account, hold stock, or grow the team. An EOR also does not remove permanent-establishment risk if those staff effectively run your UK business, for example by regularly concluding contracts.
And if you only sell to UK customers remotely, with no UK staff or office, you may need none of these: you can usually keep trading from your existing company, subject to VAT and tax rules.
Which should your overseas company choose?
Start from what the UK operation will actually do.
- Selling remotely to UK customers, no UK staff or office: usually neither. Keep trading from your existing company and check VAT.
- Hiring one or two UK people to test the market: an Employer of Record, or a small subsidiary if you also need UK contracts or a bank account.
- Building a UK sales team and signing UK enterprise contracts: a subsidiary.
- Importing and holding stock for UK distribution: a subsidiary acting as importer and seller.
- An office that supports contracts your parent signs, with no wish for a second company: a branch, if the parent accepts direct liability and publishing its accounts.
- Raising investment for the UK business: a subsidiary.
Example: a US software company. It wants UK salespeople and contracts with UK enterprises. A subsidiary lets the UK company employ the team and sign in a UK name, while the group decides which company owns the software and receives the revenue. For US groups, see Set Up a UK Company from the USA.
Example: a German engineering firm. It wants a UK site office to support projects the German company has already signed. A branch keeps the contracts in the German company, which accepts it is liable for the UK site.
Can a branch become a subsidiary later?
Yes, but it is a transfer, not a box to tick: a new UK company is formed and contracts, staff, assets and registrations move across, which can have tax and legal consequences. If you expect to grow, plan for a subsidiary from the start.
Mistakes overseas companies make
- Putting the shares in the director's personal name when the parent company should own them. The result is not a subsidiary of the group.
- Thinking a branch protects the parent. It doesn't: the parent is the branch.
- Forgetting the branch's public accounts obligation, which can expose the whole group's figures.
- Assuming a Companies House registration settles tax. Permanent-establishment tax is a separate test.
- Judging by the registration fee. £100 or £124 is nothing next to the yearly accounts, tax and admin.
- Ignoring PSC and "relevant legal entity" reporting for the parent and any holding companies above it.
- Leaving intercompany agreements until later. Funding, management fees and IP licences should be set up at the start.
What does each structure cost?
Government fees (2026)
- Subsidiary: £100 to incorporate online, then £50 a year for the Confirmation Statement.
- Branch: £124 to register the UK establishment, then £50 online or £110 on paper to file the overseas company's accounts.
With Seven Oak Prestige
- UK subsidiary formation: our packages start at £199 including the £100 Companies House fee, with no VAT added. Prestige (£299) adds a London registered office and director service address for 12 months. Because a corporate parent needs extra ownership and document checks, we confirm the final quote after reviewing the parent company's details.
- Accounting: from £699 a year for annual accounts, Corporation Tax return and Confirmation Statement. Group companies may need audit or wider reporting; we confirm the scope first. See UK Subsidiary Accounting, Tax & Compliance.
- Branch registration: we don't offer a fixed package; specialist legal help is often needed for the parent's certified documents.
Frequently asked questions
What is the difference between a UK branch and a subsidiary?
A subsidiary is a separate UK company owned by the overseas parent. A branch is the overseas company itself, registered in the UK as a UK establishment.
Is a subsidiary better than a branch in the UK?
For most overseas companies that hire, sign UK contracts or need a UK bank account, yes. A branch suits a parent that wants to keep UK activity inside its own company and accepts direct liability.
Is a UK branch cheaper than a subsidiary?
Not really. The branch fee is £124 against £100, and the parent's accounts, translations and tax attribution often make a branch more expensive to run.
Does a UK branch have to file the parent's accounts?
Usually yes. Most overseas companies with a UK establishment file their accounts at Companies House, which makes them public.
Is a branch taxed in the UK?
Yes, on the profits attributable to its UK permanent establishment.
Can an overseas company own 100% of a UK subsidiary?
Yes. The parent can be the only shareholder, and no UK-resident director is required.
What is a foreign subsidiary in the UK?
A UK limited company whose shares are owned by a company registered abroad.
Subsidiary or Employer of Record: which is better for hiring in the UK?
An Employer of Record is quicker for one or two hires. A subsidiary is better once you need UK contracts, a bank account, more staff or a long-term presence.
How long does it take to set up a UK subsidiary?
Usually 24 to 48 hours after documents and identity verification are ready. A branch often takes longer because of the parent's certified documents.
Can a branch be converted into a subsidiary?
Not directly. You form a subsidiary and transfer the branch's activity to it, which can have tax consequences.
Talk to us about your UK structure
Tell us your parent company's country, what the UK operation will do, whether you will hire, and whether you need a UK bank account. We will tell you which structure fits, the documents to prepare and the cost.
Message us on WhatsApp (ref SOP-SUBBR-FINAL) or email contact@sevenoakprestige.com.
Related guides:
- How to Set Up a UK Subsidiary: Costs and Steps
- UK Subsidiary Accounting, Tax & Compliance
- Set Up a UK Company from the USA
- UK Subsidiary for Indian Companies
- UK Company Formation Without Your Own UK Address
About the author
Isaac Jackson is Founder & Managing Director of Seven Oak Prestige Ltd (company number 16903092, registered office 124 City Road, London EC1V 2NX). He helps overseas companies and international founders set up and run UK companies.
This guide is general information, not legal or tax advice. Group structures, transfer pricing and permanent-establishment questions need specialist advice. Last reviewed: 20 November 2026.