UK Business Banking for Non-UK Residents
The complete banking readiness framework to prepare your UK company for a successful business banking application — built for international founders.
Banking Readiness Framework™
What Is Business Banking Readiness?
Establishing a UK Company Is Only the Beginning. Banking Readiness Determines What Comes Next.
Seven Oak Prestige
Banking
Readiness
Corporate Identity
Verification & Structure
Documentation
Legal & Commercial
Digital Presence
Website & Verification
Financial Profile
Source of Funds & Flow
Compliance
Governance & Risk
Corporate Identity
Verification & Structure
Documentation
Legal & Commercial
Digital Presence
Website & Verification
Financial Profile
Source of Funds & Flow
Compliance
Governance & Risk
Overview
Executive Summary
For international founders and non-UK residents, forming a UK Limited company is a straightforward administrative process. However, opening a UK business bank account or securing an Electronic Money Institution (EMI) account is entirely different. It is a risk-weighted compliance decision made by heavily regulated financial institutions.
The Banking Readiness Framework™ is the due diligence standard used to evaluate whether your business is prepared for the scrutiny of UK financial institutions.
What Is Business
Banking Readiness?
Financial institutions in the UK operate under strict
A "Banking Ready" company is one that presents a transparent, verifiable, and low-risk profile that aligns with the compliance requirements of UK banking providers.
Failure to demonstrate readiness usually results in immediate rejection, which can severely impact your ability to open an account with other providers in the future.
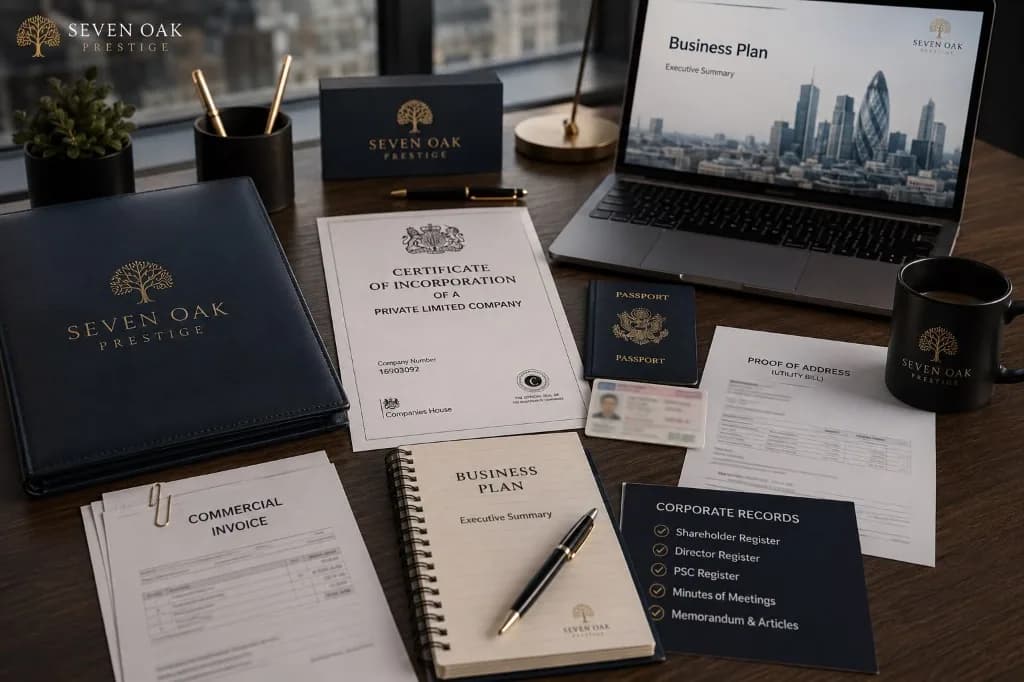
A Banking Ready company demonstrates:
A Banking Ready company demonstrates:
Banking Readiness Framework™
The Five Pillars of Readiness
The framework is divided into five critical pillars. Each pillar represents a core area of risk assessment used by compliance teams.
Corporate Identity
Foundational structure and verifiable identity.
Corporate Identity Assessment
Business Documentation
Evidence of commercial legitimacy.
Business Documentation Checklist
Website & Digital Presence Readiness
Public-facing commercial footprint.
Digital Presence Assessment
Financial Readiness
Transparency of funds and transaction flow.
Financial Readiness Checklist
Compliance & Corporate Governance
Adherence to UK regulatory frameworks.
Compliance Verification
Assessment
The Banking Readiness Score™
Before applying, assess your company against the 100-point scorecard. A score below 80 indicates a high probability of rejection.
Maximum Potential Score
Achieving a perfect score signifies a robust corporate profile ready for banking due diligence.
Assessment Matrix
Excellent Readiness
Your business demonstrates a strong level of organisational preparation and corporate consistency.
Good Readiness
Most key elements appear to be in place. Review any remaining gaps before beginning an application.
Developing Readiness
Several important areas may benefit from further preparation to create a complete business profile.
Preparation Recommended
Consider reviewing your business structure, documentation, and compliance arrangements.
Evaluate Your Banking Readiness
Take our 20-question assessment to calculate your Banking Readiness Score™. Identify gaps in your corporate profile before you apply for a UK business bank account.
Execution
30-Day Banking Preparation Timeline
Follow this structured timeline to prepare your application systematically.
Foundation & Identity
Establish the corporate entity and secure core documentation.
- Incorporate UK Company with appropriate SIC codes
- Secure premium Registered Office and Director Service Address
- Obtain certified identity and address documents
- Set up professional domain, email hosting, and UK phone number
Commercial Evidence
Build the digital presence and commercial justification.
- Develop and publish professional website with legal pages
- Finalise comprehensive business plan and financial projections
- Gather draft contracts, LOIs, and supplier agreements
- Register for ICO (Data Protection) if required
Application Assembly
Compile the dossier and submit to selected institutions.
- Review all documentation against the 5-Pillar Framework
- Select primary and secondary banking/EMI targets
- Submit applications with complete supporting documentation
- Prepare for potential compliance interviews or RFI (Request for Information)
Knowledge Base
Frequently Asked Questions
Common questions regarding banking readiness for non-residents.
Can I guarantee that my bank account will be opened?
No. No agency or formation agent can guarantee the opening of a UK business bank account. The final decision always rests with the compliance department of the financial institution. We can only guarantee that your application is prepared to the highest possible standard.
Do I need to visit the UK to open an account?
Generally, no. Most EMI (Electronic Money Institution) and challenger banks allow remote onboarding for non-residents. High-street banks (Barclays, HSBC, Lloyds) often require a face-to-face meeting, though this is changing for certain established businesses.
What is an EMI?
An Electronic Money Institution (e.g., Wise, Revolut, Payoneer). EMIs are regulated by the FCA and offer business accounts with sort codes and account numbers, but they are not 'banks' in the traditional sense (they do not lend money and may not be covered by the FSCS, though funds are safeguarded).
Why was my application rejected previously?
Common reasons include: lack of UK footprint (website/address), high-risk industry (crypto, gambling, complex import/export), mismatch between SIC codes and business plan, or inability to verify the source of funds.
Resource
Download the Executive Banking Readiness Checklist
Get the complete 100-point evaluation matrix and actionable preparation steps delivered to your inbox.
Download PDF GuideAdvisory Services
Request an Advisory Consultation
Seven Oak Prestige assists international entrepreneurs in preparing their businesses, documentation, and operational profiles to support a structured and professional UK expansion.
Request an Advisory ConsultationPrepared by Seven Oak Prestige LtdThis guide has been prepared by Seven Oak Prestige Ltd to help international entrepreneurs understand the practical considerations involved in preparing a UK business for banking and payment provider onboarding. It is reviewed periodically to reflect changes in UK corporate compliance practices and is intended for general educational purposes.